
An EMV device is a payment terminal that reads smart chips embedded in credit and debit cards, providing higher security than magnetic stripes.
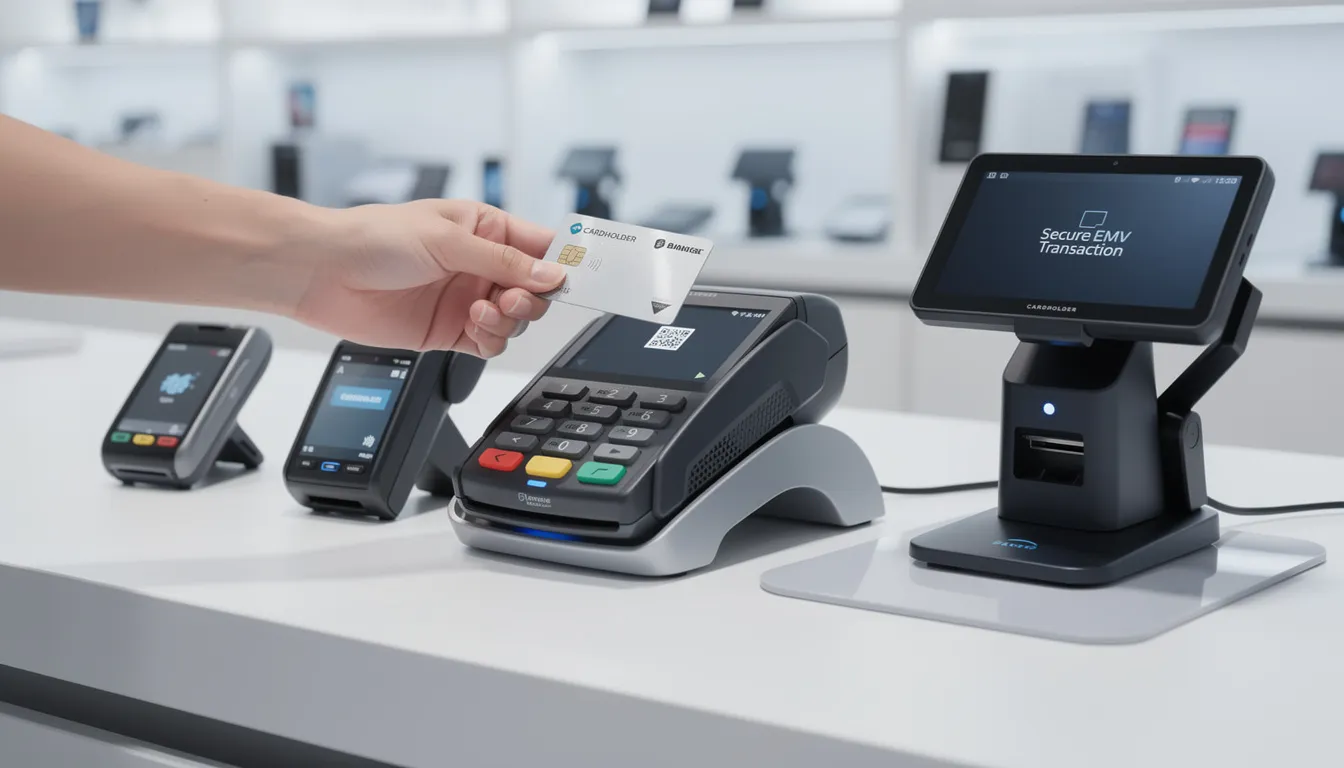
Summary: What Is an EMV Device and Why Does It Matter?
An EMV device is a payment terminal that reads smart chips embedded in credit/debit cards, providing higher security than magnetic stripes. EMV terminals are designed to process transactions using chip technology, which enhances security compared to magnetic stripe readers. EMV terminals can significantly reduce the risk of credit card fraud and unauthorized transactions for both merchants and customers.
Introduction
This guide is for payment system integrators, IT managers, and retail operators seeking reliable EMV device rollouts. It covers EMV device types, integration models, procurement criteria, and deployment best practices to ensure secure, scalable, and supportable payment solutions.
Introduction to EMV Technology
EMV technology is the global standard for secure payments, transforming how credit and debit card transactions are processed at the point of sale. EMV stands for Europay, Visa, and Mastercard, which are the credit card companies that developed this chip technology. Unlike traditional magnetic stripe cards, EMV chip cards (often called chip cards) contain a microprocessor chip that securely stores and processes card data. This chip technology makes it far more difficult for fraudsters to clone cards or steal sensitive information, providing a significant upgrade in payment security. Today, EMV technology is the backbone of secure payments worldwide, with over 96% of card transactions relying on EMV chips to protect both merchants and customers. As the industry standard, EMV ensures that every transaction is processed with advanced security, reducing the risks associated with magnetic stripe cards and setting a new benchmark for secure, reliable payments.
Procurement Conclusion for Integrators and Multi-Location Operators
Choose an EMV device only after you lock (1) the payment architecture, (2) the counter’s cabling/port reality, and (3) the lifecycle plan for spares, swaps, and version control—otherwise your rollout risk shows up later as downtime and truck rolls.
If you’re standardizing full checkout hardware (not just payments), start from your complete hardware stack under POSZEO Products and treat the EMV layer as one part of a deployable system.
What an EMV Device Is (and What It Is Not)
People search for “EMV device” because they want secure card acceptance—but the term hides multiple device classes that behave very differently in deployment.
An EMV device is a payment terminal that reads smart chips embedded in credit/debit cards, providing higher security than magnetic stripes.
Practical Mapping: Types of EMV Devices
- EMV chip terminal: A payment terminal that supports chip (and often contactless) transactions from a physical card, specifically EMV chip cards. These terminals are often referred to as POS terminals, which are the hardware that processes EMV chip card transactions. Depending on the architecture, it may be standalone, semi-integrated, or fully integrated into a POS workflow. Note: EMV chip cards are equipped with both a chip and a magnetic stripe for backward compatibility with older systems.
- EMV chip readers: A broader category that can include countertop readers, mobile readers, PIN pads, or integrated readers built into a POS housing. These devices are used to read the physical card and facilitate secure payment processing.
- Card reader chip: A confusing phrase. In procurement conversations, it usually means “chip-card reading capability” (EMV support). In engineering conversations, it can also mean the internal secure module components. For buying and rollout planning, treat “card reader chip” as a requirement for chip reading, plus the certifications and integration model that come with it.
What an EMV Device Is Not
- Not your POS workstation. Your POS workstation is the system that runs your POS app and connects peripherals (printer, cash drawer, scanner, display). For fixed checkout systems, that’s typically a desktop-class solution such as Desktop POS Systems.
- Not a guarantee of compatibility. An EMV device can be “EMV-capable” and still fail in real deployments if cabling, drivers, SDK versions, or network segmentation are not planned.
- Not the same as traditional payment terminals that were often installed in a fixed location, such as a store counter, which limited flexibility compared to modern mobile or integrated EMV devices.
In other words: “EMV-capable” is table stakes. Integrator-ready means predictable integration, predictable support, and predictable replacement.
Now that we’ve clarified what an EMV device is, let’s explore how integration choices affect deployment.
Decision Tree: Standalone vs Semi-Integrated vs Integrated EMV

Before you compare models, decide how the EMV device will interact with the POS. The choice of EMV device integration directly impacts how payment data is handled and processed by the payment processor and POS software. POS software must be compatible with the EMV device to ensure secure handling of payment data throughout each transaction.
When considering integration, remember that the payment processor acts as a key intermediary, facilitating secure EMV transactions between the EMV device, the POS system, and the card issuer. This ensures that sensitive payment data is protected and transactions are processed efficiently.
1) Standalone EMV Chip Terminal (Lowest Integration, Fastest Swap)
A standalone EMV chip terminal processes the payment by itself, then the cashier records the tender in the POS (or the POS consumes a receipt/confirmation output).
Why teams choose it:
- Minimal integration effort
- Straightforward field replacement (swap the terminal, keep selling)
- Lower dependency on POS OS updates and drivers
Where it can cost you later:
- Reconciliation exceptions (POS vs payment settlement mismatches)
- Weaker centralized control over prompts, flows, and exception handling
- More manual work at scale
Standalone is not “wrong”—it’s a conscious tradeoff between integration simplicity and operational automation.
2) Semi-Integrated EMV (Common in Professional Rollouts)
Semi-integrated EMV typically means the POS initiates the payment request and receives the result, but the EMV device remains a semi-independent payment endpoint.
Why it’s popular:
- Better cashier workflow and fewer manual errors
- Clearer tender states in the POS (approved/declined/canceled)
- A practical balance of integration and serviceability
- Semi-integrated EMV solutions provide additional security by ensuring that payment data is transmitted as encrypted data directly from the EMV device to the payment processor, reducing the risk of data breaches.
What you must validate:
- Interface and transport (USB, Ethernet, serial) between the POS and the EMV device
- SDK/middleware versioning
- Repeatable staging + verification scripts
Semi-integrated deployments often succeed when you treat the EMV device like any other peripheral: it needs an interface contract, a version contract, and a support plan.
3) Integrated EMV (Tight Coupling, Higher Control, Higher Discipline)
Integrated EMV usually offers the smoothest customer experience and the most consistent transaction workflow—but it requires strict control over the software and firmware ecosystem.
You gain:
- Unified transaction flow and tighter POS control
- Seamless EMV transactions and EMV chip card transactions, enabling secure authentication methods for cardholders such as PIN entry or signature verification
- Cleaner refunds/voids behavior when implemented correctly
- Better multi-lane standardization when versions are managed
You inherit:
- More moving parts (drivers, services, OS patches, SDK changes)
- Higher sensitivity to “version drift.”
- More demanding staging, rollback, and incident response practices
For multi-location brands, integrated EMV only works when your rollout process is engineered: staging, change control, and support escalation must be defined up front. That’s why many teams formalize rollout steps through a deployment playbook, such as POS Deployment Service.
With integration models defined, let’s move on to the key criteria that determine successful EMV device rollouts in real-world environments.
The Buyer Criteria That Matter in Real Stores
For SHOPPING-intent buyers, feature lists are easy. What prevents rollout failures are the boring criteria: ports, cables, environment, and serviceability.
Buyers should also consider how EMV devices handle card expiry date checks, as verifying the expiry date is essential to prevent fraudulent transactions. If merchants do not use EMV-capable systems, they may be held liable for fraudulent transactions, making the selection of the right device critical for effective risk management.
Countertop vs Mobile vs Embedded
An EMV device is as much about counter workflow as it is about payments.
- Countertop EMV: Stable, cabled, predictable—best for fixed lanes with higher throughput.
- Handheld/mobile EMV: Useful as a relief valve (line-busting, curbside, queue busting) or as a redundancy strategy. These devices often support contactless cards and near field communication (NFC) technology, enabling customers to pay quickly by tapping their card or smartphone.
- Embedded/integrated EMV: Clean design, fewer external boxes—requires stronger lifecycle control.
If you plan mixed-mode checkout (fixed lanes + assisted mobile), validate that your payment architecture supports both without splitting reporting and support workflows.
Peripheral Stack Fit
In real stores, the payment flow touches:
- Printer (receipts, sometimes cash drawer kick logic indirectly)
- Cash drawer (trigger path must be deterministic)
- Scanner (fast SKU entry; refunds and returns often depend on scan workflows)
- Customer display (reduces disputes; improves confirmation)
Note: The EMV device and peripheral stack must support secure transactions for both credit and debit cards to ensure comprehensive payment acceptance and enhanced security.
Your EMV device decision must be compatible with the full hardware stack and the POS OS environment—not just the payment gateway.
Ports & Connectivity
Most rollout pain comes from port assumptions.
Create a port map that lists:
- POS ports required by each peripheral
- EMV device interface needs (USB/Ethernet/serial)
- Network requirements (wired vs Wi-Fi; VLAN segmentation expectations)
- Power bricks and cable routing requirements
This is where teams discover that “it works in a demo” is not the same as “it installs cleanly in 60 minutes at every site.”
Payment Integration Impact
Changes will happen: new POS versions, OS patches, gateway updates, and EMV firmware changes.
Buyers should require:
- A stable integration approach (standalone / semi-integrated / integrated)
- A versioning plan and a test script
- A rollback path that does not require a full store rebuild
Serviceability & Lifecycle
Treat EMV hardware as field equipment:
- Define which parts are hot-swappable
- Stock spare devices and the most common failure accessories (cables, PSUs)
- Track device IDs and location assignments to prevent “mystery swaps”
If you want EMV uptime across many sites, it’s not enough to buy an EMV device—you must buy a service model.
With these criteria in mind, let’s see how to match EMV hardware to your checkout workflows using a practical selection matrix.
Selection Matrix: Match EMV Hardware to Checkout Workflows
Use the matrix below to choose an EMV device based on integration risk, rollout effort, and serviceability—not marketing claims. The matrix helps businesses select the right EMV device for accepting EMV credit cards and EMV cards, whether for in-person transactions or online payment scenarios.
EMV Device Selection Matrix (Integrator-Ready)
| EMV Setup | Best For | Typical Components | Integration Risk | Rollout Effort | Serviceability at Scale |
|---|---|---|---|---|---|
| Standalone EMV chip terminal | Simple acceptance, fast swap | Terminal + network | Low–Medium | Low | High |
| Semi-integrated EMV (PIN pad/reader) | Professional checkout flow | POS + EMV reader/PIN pad | Medium | Medium | Medium–High |
| Fully integrated EMV | Standardized UX + control | POS + integrated EMV stack | Medium–High | Medium–High | Medium |
| Hybrid (fixed + mobile backup) | Peak lines + resilience | Countertop + mobile reader | Medium | Medium | High when standardized |
How to use it:
Pick the row that matches your operational reality, then lock the interface contract (ports, cables, network), then select device candidates. If you select devices first, you’ll end up designing your rollout around the weakest constraint.
For hardware teams that also need the full POS device ecosystem (not just payments), centralize your peripheral and accessory planning under POS Accessories & Peripherals so the EMV layer doesn’t become an isolated purchase.
With your selection approach defined, let’s address the practical risks of ports, cabling, and adapters at the counter.
Ports, Cabling, and “Adapter-Chain Risk” at the Counter

EMV deployments fail in predictable ways—especially at counters built over time with mixed legacy hardware.
Why Adapter Chains Are a Real Risk
Adapter chains (USB hubs, USB-to-serial, USB-to-Ethernet, dongles) add failure points:
- Intermittent disconnects
- Power draw issues
- Port negotiation or enumeration problems after OS updates
- “Works today, fails next week” are symptoms that are expensive to diagnose
Practical Counter Rules That Reduce Incidents
- Prefer wired Ethernet for fixed checkout payment traffic when feasible.
- Treat USB hubs as planned infrastructure, not an emergency patch.
- Standardize cable lengths and routing so every site looks the same behind the counter.
- Document port assignments so field techs don’t “swap until it works.”
If you standardize the counter design, your troubleshooting becomes repeatable. If every site is unique, your support becomes artisanal—and slow.
Next, let’s ensure your EMV device works seamlessly with the rest of your checkout peripherals.
Peripheral Stack Compatibility: Printer, Cash Drawer, Scanner, Customer Display
Your EMV device is only “successful” if the full checkout loop is stable.
Receipt Printing and Drawer Behavior
Many environments couple cash drawer behavior to printer signals or specific port behavior. That means a “small change” (printer model, driver, or cable) can ripple into cash operations.
Verification checks you should run at staging:
- Sale → EMV approved → receipt prints → drawer opens
- Void/refund → receipt behavior matches policy
- Reprint workflows do not hang the POS UI
- Drawer opens only on expected tender types (policy-driven)
Scanner Workflows Drive Speed and Error Rates
Scanners vary in how they present input (keyboard wedge modes, configured prefixes, etc.). In rollouts, standardize:
- Scanner configuration
- Test scripts for returns, coupons, and price checks
- How the POS handles partial scans or failures
Customer Display Reduces Disputes
Customer-facing confirmation reduces “I didn’t authorize that” friction and shortens resolution time for cashier disputes—especially when combined with consistent EMV prompts.
For industry-specific checkout patterns and store workflows (retail, restaurant, pharmacy, etc.), anchor your rollout expectations in a solution blueprint such as POSZEO Solutions and align the EMV device choice to that workflow—not to a generic “best device” list.
With your peripheral stack aligned, let’s review the security features that make EMV technology the global standard.
Security Features of EMV
EMV technology is designed with advanced security features that dramatically reduce the risk of credit card fraud. Each time an EMV chip card is used, the chip generates a unique code for that specific transaction, making it extremely difficult for criminals to duplicate card information or create counterfeit cards. This dynamic authentication process is a major improvement over the static data stored on magnetic stripe cards, which can be easily copied. EMV card readers further enhance security by encrypting and tokenizing sensitive card data during payment processing, ensuring that cardholder information remains protected throughout the transaction. The chip technology also supports secure contactless payments, allowing customers to simply tap their chip cards or compatible devices for fast, secure transactions. By leveraging these advanced security features, EMV technology helps merchants and customers stay ahead of evolving fraud tactics and ensures that every credit card transaction is processed with the highest level of protection.
With security as the foundation, let’s look at how to stage, control, and verify your EMV deployment for long-term success.
Deployment Notes: Staging, Version Control, and Site Verification

An EMV rollout is a lifecycle project. Treat deployment as a product, not a one-time installation.
1) Staging (Pre-Configure Everything)
Build a standard staging package:
- POS OS baseline + patch level
- POS app version
- EMV integration layer versions (middleware/SDK settings)
- Network profiles and firewall rules
- Peripheral driver baselines
- A “known-good” configuration snapshot
2) Change Control (Freeze What Must Be Frozen)
Define what can change without re-certification or retesting, and what cannot. In practice:
- EMV integration components should follow a controlled release cadence
- OS updates require re-running the verification script
- Peripheral firmware changes should be treated as change events, not background noise
3) Site Verification (Run the Same Script Everywhere)
A repeatable acceptance script prevents “mystery issues”:
- Chip insert transaction
- Contactless tap transaction
- Decline path handling
- Refund/void flows
- Receipt and drawer behavior
- Network failover expectations (if your business requires it)
When you formalize this, support teams can diagnose faster, and you avoid shipping blame between vendors. For ongoing operational support processes, align escalation and response routines with a helpdesk model like POS Technical Support.
With deployment best practices in place, let’s consider how regional differences may affect your EMV rollout.
Regional Considerations
The adoption of EMV technology varies significantly by region, and understanding these differences is crucial for merchants and payment processors planning new rollouts. In the United States, the 2015 liability shift prompted a rapid increase in the acceptance of EMV chip cards, as merchants who did not accept EMV chip transactions became liable for certain types of fraud. This shift accelerated the deployment of EMV chip readers and chip cards across the country. In contrast, Europe has long been a leader in EMV adoption, with most countries achieving near-universal use of EMV technology for both credit and debit card payments. When implementing payment solutions, merchants must consider these regional differences—not only in terms of technology, but also in liability and compliance requirements. Accepting EMV chip cards is now a baseline expectation in many markets, and failing to do so can expose merchants to increased liability and lost business opportunities. Always align your payment strategy with local EMV adoption rates and regulatory expectations to ensure a smooth, compliant rollout.
With regional context in mind, let’s focus on how to keep your EMV hardware serviceable and resilient over its lifecycle.
Serviceability & Lifecycle: Spares Pool, Swap Model, and RMA Loop
Rollout success is measured in uptime, not installation day.
Build a Spares Pool That Matches Downtime Cost
At a minimum, spares planning should include:
- EMV device spares per store cluster or region
- Spare cables and power supplies (high failure rate, low cost)
- Spare printer components where receipts are business-critical
Define Your Swap Model
Decide:
- Who swaps the EMV device (store staff vs technician)
- What’s the re-provisioning workflow (pairing, configuration, gateway enrollment)
- How do you prevent “random swaps” that break asset tracking
Make RMA a Closed Loop
A reliable RMA loop includes:
- Failure classification (DOA vs field failure)
- Required logs and configuration snapshots
- Packaging rules to prevent return damage
- Root-cause feedback (cable strain, power issues, network instability)
For organizations that want fewer incidents over time, schedule routine health checks and version alignment under a maintenance plan like POS Maintenance Service.
With lifecycle management in place, let’s review the most common failure modes and how to prevent costly truck rolls.
Common Failure Modes and How to Prevent Truck Rolls
These failure modes show up repeatedly in EMV deployments—each has a prevention check you can run before go-live.
- Integration version drift (POS app, SDK, EMV firmware misaligned)
- Prevent: Lock versions per release; retest chip + tap + refund flows after any change.
- Adapter-chain instability (dongles/hubs create intermittent disconnects)
- Prevent: Require a documented port map; validate full peripheral load in staging; minimize unplanned adapters.
- Network segmentation gaps (payment traffic mixes with guest Wi-Fi or unstable networks)
- Prevent: Define VLAN/firewall rules; validate DNS and outbound destinations; prefer wired Ethernet for fixed counters.
- Cable strain and counter ergonomics (ports loosen, devices disconnect under daily use)
- Prevent: Mount planning + strain relief; standard cable lengths; route cables away from high-touch zones.
- Peripheral coupling surprises (printer changes break drawer behavior; scanner modes break workflows)
- Prevent: Standardized peripheral SKUs; run an acceptance script that includes receipt/drawer/scanner flows.
- Support handoff failures (no asset tracking, inconsistent troubleshooting steps)
- Prevent: Asset ID policy, ticket templates, and a defined escalation path; train staff on “what not to change.”
- Training gaps (staff force reboots, bypass flows, or mishandle declines)
- Prevent: Role-based onboarding and job aids; confirm proficiency during rollout. If needed, formalize with the POS Training Service.
If you solve these upfront, your EMV device selection stops being a gamble and becomes an engineered outcome.
With failure prevention in mind, let’s highlight common mistakes to avoid during EMV implementation.
Common Mistakes to Avoid
Implementing EMV technology brings significant security benefits, but only if done correctly. One of the most common mistakes merchants make is failing to properly configure EMV card readers, which can leave payment systems vulnerable to attacks or operational issues. Another frequent oversight is neglecting to keep EMV technology, including software and firmware, up to date—outdated systems are more susceptible to security breaches and may not support the latest payment features. Additionally, using non-compliant or uncertified EMV card readers can compromise both security and transaction reliability.
To avoid these pitfalls:
- Ensure all EMV devices are properly configured
- Regularly update software and firmware
- Verify that all hardware is fully compliant with current EMV standards
Taking these steps will help safeguard your payment environment and maintain the integrity of every transaction.
With mistakes to avoid in mind, let’s look at practical BOM examples you can use for your RFPs.
BOM Examples You Can Copy Into an RFP
Below are reference BOMs (no pricing) designed to be deployable and serviceable. EMV terminals are designed to process transactions using chip technology, which enhances security compared to magnetic stripe readers. When choosing an EMV terminal, businesses should consider transaction volume, mobility needs, and integration with existing POS systems. Advanced security features like end-to-end encryption and tokenization are important for protecting sensitive customer data.
There are two types of EMV chip cards: Chip and PIN, which require the cardholder to enter a PIN to authenticate the transaction, and Chip and Signature, which require a signature for verification.
Contact EMV readers require customers to insert their card and enter their PIN, while contactless EMV readers allow customers to pay by tapping their card or phone on the reader for faster transactions. Mobile EMV readers can sync with smartphones for secure payments on the go, and businesses can connect a phone or tablet to their EMV card reader using Bluetooth for a portable payment processing solution.
BOM A: Fixed Counter Retail Lane (Standardized, High Throughput)
- POS workstation: fixed desktop POS class (touch + adequate I/O)
- EMV device: semi-integrated EMV reader/PIN pad (chip + contactless)
- Receipt printer: wired thermal printer
- Cash drawer: compatible trigger path + spare cable
- Barcode scanner: wired, standardized configuration
- Customer display: dual-screen or customer-facing display
- Network: dedicated Ethernet drop for checkout
- Spares: 1 EMV spare per store cluster + spare PSUs/cables
BOM B: Quick-Service Counter (Fast Recovery)
- POS workstation: fixed counter POS
- EMV chip terminal: standalone or semi-integrated, depending on workflow
- Printer + drawer: standardized pairing
- Spares: prioritize the EMV device and printer PSU
BOM C: Multi-Location “Counter Kit” (Rollout-First SKU Thinking)
- One standardized kit definition containing:
- Port map
- Cable pack (labeled)
- Mounting accessories
- Staging package reference
- Acceptance script checklist
- Spares policy: region-based spares pool + swap model documentation
A good BOM reads like a deployment plan—not like a shopping cart.
With BOMs in hand, let’s wrap up with a step-by-step checklist for EMV device procurement.
Procurement Wrap-Up: The Step-by-Step Buyer Checklist
Use this checklist to choose an EMV device that will hold up in real-world rollouts. Data security is a key reason for adopting EMV technology, as it protects customer payment data and reduces liability for fraud. EMV terminals play a crucial role in ensuring secure EMV transactions for both merchants and customers by significantly reducing the risk of credit card fraud. Remember, the liability for fraudulent transactions shifts to merchants if they do not use EMV-capable systems, making EMV adoption essential. Adopting EMV technology also helps businesses improve customer trust and credibility by demonstrating a commitment to security.
Step-by-Step Buyer Checklist (RFP-Ready)
- Define what “EMV device” means in your project (standalone terminal, semi-integrated reader/PIN pad, or integrated EMV).
- Lock the payment architecture and document why it fits your support model.
- Build a port map for the full counter: EMV, printer, cash drawer, scanner, customer display, network, and power.
- Decide counter connectivity: wired Ethernet vs Wi-Fi, and the segmentation rules.
- Standardize the peripheral stack SKUs to avoid mid-rollout substitutions.
- Require a staging package: versions, settings, enrollment steps, and a rollback method.
- Write and run a site acceptance script (chip, tap, decline, refund/void, receipt, drawer, scanner).
- Define serviceability: spares pool, swap model, and RMA loop with asset tracking.
- Establish support escalation and ticket templates to keep troubleshooting repeatable.
- Train store staff on the approved workflows and “do not change” rules.
If you follow this order, selecting an EMV chip terminal or EMV chip readers becomes a controlled decision—one you can deploy, support, and scale without surprises.
With your procurement process complete, let’s look ahead to the future of EMV technology.
Future of EMV Technology
The future of EMV technology is centered on delivering even greater security and convenience for both merchants and customers. One of the most significant trends is the rapid growth of contactless payments, which allow customers to pay quickly and securely by tapping their EMV chip cards or compatible devices. Mobile wallets like Apple Pay and Google Pay are also gaining traction, leveraging EMV technology to process transactions securely through smartphones and wearables. As payment technology continues to evolve, EMV is expanding to support new payment methods, including IoT devices and advanced authentication techniques. These innovations are making payment processing faster, more flexible, and more secure than ever before. For businesses, staying current with EMV technology means being ready to accept the latest payment options while maintaining robust security for every transaction. As the foundation of modern payment processing, EMV will continue to play a critical role in enabling secure, innovative payment experiences for years to come.


Duplicate Kitchen Tickets in Multi-Printer POS: What to Check Before Replacing Hardware

POS Connectivity Issues During Peak Hours: Causes, Impact, and Solutions

POS Receipt Compliance in the US

Docked vs Roaming Handheld POS: The Real Rule for USB and Networked Accessories

POS Customer Display Ports: HDMI, USB, VGA, Serial, and USB-C Explained

Restaurant Order Routing: When a KDS Should Replace Kitchen Printers—and When It Should Not

Restaurant POS Station Map: How to Assign Terminals, Handhelds, Printers, and KDS by Zone

Android POS App Update Rollout Guide

Price-Calculating Scale vs Weight-Only Scale for POS: What Changes in Software Logic, Auditability, and Rollout Risk


