
A mobile pay device is a field-deployed endpoint designed for flexible, in-person transactions in B2B environments. Explicitly, a mobile pay device refers to any hardware or smart device that enables businesses to accept payments on the go, including smartphones, smartwatches, card readers, and all-in-one terminals. A mobile payment device can be a smartphone or smartwatch acting as a digital wallet, utilizing NFC, QR codes, and apps for secure, contactless, and in-app transactions. These devices support a range of payment technologies, such as NFC (Near Field Communication) for tap-to-pay, QR code scanning, and digital wallets like Apple Pay, Google Pay, and Samsung Pay. Digital wallets hold digitized credit/debit cards, loyalty cards, and tickets, and are often pre-installed or compatible with popular mobile devices.

Overview: Main Types of Mobile Payment Devices and Technologies
Popular mobile payment devices include:
- Smartphones and Smartwatches: Act as digital wallets, using NFC, QR codes, and apps for secure, contactless, and in-app transactions.
- Card Readers: Compact devices like Zettle by PayPal and Square Reader, and mobile handheld POS devices for field use, which connect via Bluetooth and accept chip, contactless, and magstripe payments.
- All-in-One Terminals: Devices such as Clover Flex and Clover Terminal, which operate over Wi-Fi or LTE and include touchscreens for standalone payment processing.
- Digital Wallets: Services like Apple Pay (pre-installed on iPhones and Apple Watches), Google Wallet (Android-based), and Samsung Pay (for Samsung devices), which store digitized cards and enable tap-to-pay via NFC.
- NFC (Near Field Communication): The most common technology for tap-to-pay, used by Apple Pay, Google Wallet, and Samsung Wallet. Enables contactless payments by bringing a device within a few centimeters of a POS terminal.
- QR Code Payments: Involve displaying or scanning a QR code at checkout to process payments.
- Offline Transactions: Some devices allow for offline payments when there is a weak or limited connection.
- Portability: Many mobile payment devices are designed to be portable and compact, suitable for on-the-go transactions in various business settings, such as pop-up shops and off-site events.
These technologies enable businesses to accept a wide range of payment methods, including EMV chip cards, contactless cards, magstripe cards, and digital wallets, while providing features like digital receipts, inventory management, and enhanced security through encryption and tokenization. (Fact 1–53)
Introduction to Mobile Payments
Mobile payments have transformed the way businesses accept payments, making it possible to process transactions securely and efficiently from virtually anywhere. As contactless payments become the norm, solutions like Apple Pay and Google Pay are now expected by customers in both retail and B2B environments. With a mobile phone or tablet, businesses can accept payments on the spot—whether on the sales floor, at a pop-up event, or during a delivery—eliminating the need for fixed terminals and long checkout lines.
The adoption of mobile payments enables businesses to offer a seamless, modern payment experience. Customers can simply tap their card or mobile device to pay, leveraging secure technologies that protect their data and reduce transaction friction. For businesses, this means faster payment processing, fewer abandoned sales, and the ability to accept payments wherever the customer is. As mobile payments continue to evolve, staying current with the latest contactless and digital wallet options is essential for any business looking to remain competitive and responsive to customer needs.
Benefits of Mobile Payment Devices
Flexibility for Dynamic Environments
Mobile payment devices deliver a range of benefits that go beyond simple transaction acceptance. For businesses operating in dynamic environments—such as pop-up shops, events, or mobile service locations—these devices provide unmatched flexibility. Staff can accept payments using a mobile phone or tablet, allowing transactions to happen wherever the customer is, not just at a fixed counter.
Contactless Payment Support
Supporting contactless payments, including Apple Pay and Google Pay, is increasingly important as customers expect fast, touch-free checkout experiences. By enabling customers to pay with a tap, businesses can reduce wait times, increase throughput, and boost overall satisfaction. This is especially valuable in high-traffic scenarios or when serving customers on the move.
Security Advantages
Security is another key advantage. Modern mobile payment devices use advanced encryption and tokenization to safeguard sensitive payment data, helping to prevent fraud and ensure secure transactions. This level of protection builds trust with customers and supports compliance with industry standards. Ultimately, mobile payment devices empower businesses to accept payments confidently, adapt to changing workflows, and deliver a superior customer experience—no matter where the sale happens.
Why “Payments on the Go” Changes Your Hardware Spec
When the business requirement is payments on the go, the selection criteria shift from “nice-to-have features” to “what fails first in the field.” For field deployments, minimizing hardware needed and ensuring easy setup are critical to fit your POS stack.
Typical Field Workflows That Drive Requirements

In B2B deployments, mobile acceptance usually shows up in one of these patterns:
- Queue-busting inside stores: Staff roam the floor to reduce checkout congestion.
- Curbside / parking-lot handoff: Staff moves between indoor Wi-Fi and outdoor dead zones.
- Delivery / last-mile: A device lives in vehicles, gets bumped, and sees harsh temperature swings.
- Pop-ups and events: Inconsistent power, variable network, fast onboarding for temporary staff.
- Hospitality line-busting: Peak-hour bursts, high transaction counts, and frequent handoffs.
Many of these workflows are now enabled by transforming a smartphone into a payment terminal using tap-to-pay technology. This allows staff to accept contactless payments directly on their smartphones without additional hardware, supporting quick, secure, and flexible in-person transactions.
Each workflow affects whether you need a handheld payment device (single-handed use, rugged handling), a more general portable payment device (lightweight, easy charging), or a broader portable payment system that includes connectivity management and centralized support.
The Failure Modes to Design Around (B2B Reality)
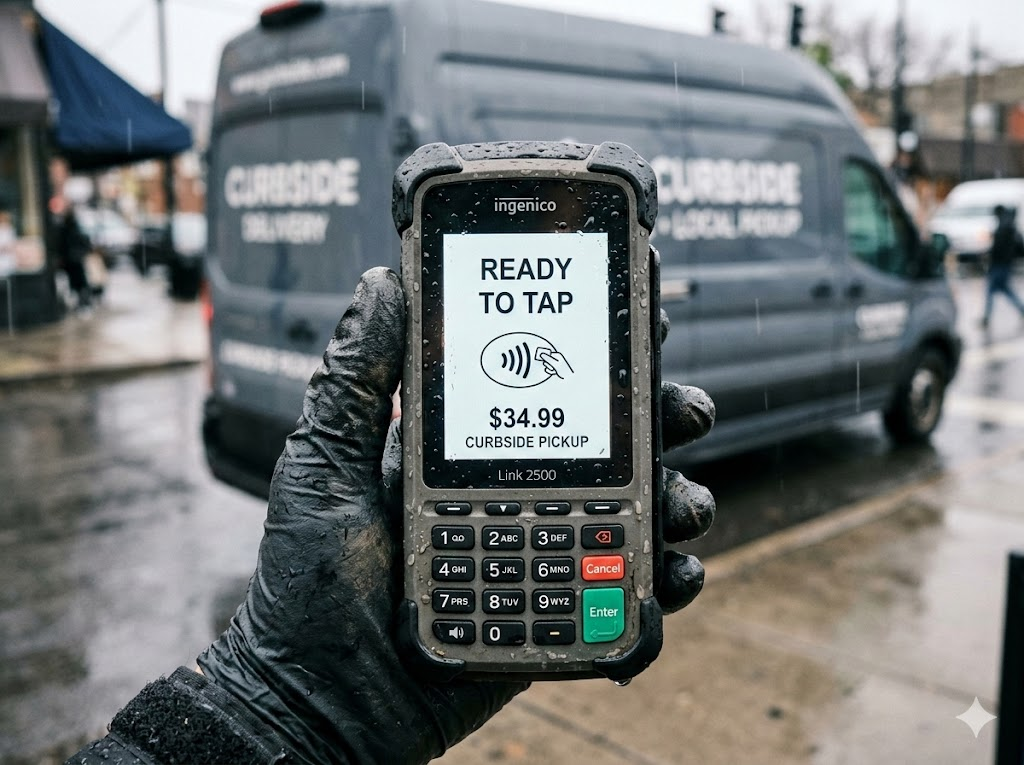
B2B buyers should model selection around the most common operational failures:
- Connectivity drop → failed authorizations, abandoned sales, longer queues
- Battery depletion mid-shift → staff shares devices, chaotic charging, lost accountability
- Physical damage (drops, screen cracks, port wear) → high RMA volume and spare stock pressure
- Software drift (inconsistent versions) → intermittent bugs, payment flow mismatches
- Support bottlenecks → each site calls IT; integrator margins get consumed by tickets
If you align device class and management approach to these failure modes early, your mobile pay device choice becomes a repeatable SKU strategy rather than a one-off “best-looking gadget” decision.
What Counts as “Pay Devices” in B2B Deployments
The keyword pay devices is broad, and that’s exactly why B2B teams should define boundaries before quoting hardware.
Types of Pay Devices
In B2B, “pay devices” can refer to:
- Payment endpoints like mobile pay devices, terminal hardware such as card readers, and contactless readers
- POS systems (fixed or mobile), including desktop all-in-one retail POS terminals
- Self-service POS kiosks for unattended checkout
- Tablets or smartphones with payment acceptance capabilities, including Android handheld POS terminals with printers
A managed bundle may include not only the mobile pay device itself, but also a supported payment app to ensure compatibility with various payment methods, as well as accessories, software, and support.
Device vs Terminal vs System (Where Responsibility Sits)
In B2B, “pay devices” can refer to:
- A payment endpoint (reader/terminal) that captures card-present input
- A smart device (Android-based handheld) running POS + payment flows
- A managed bundle—a portable payment system—including the device, SIM/eSIM strategy, MDM controls, app distribution, and support processes
Your procurement scope determines what you can standardize. Integrators and distributors typically win on repeatability, so it’s worth deciding whether your offering is:
- Hardware-only (customer manages software and updates)
- Hardware + managed software image (you control versions)
- Hardware + managed operations (you own the ongoing health of the fleet)
Procurement Boundaries That Reduce Rollout Friction
Before you finalize a payment device SKU, define:
- Who owns payment application configuration and updates?
- Who handles device provisioning and identity (store, staff, terminal IDs)?
- Who owns replacements and swap logistics?
- What’s the minimum viable accessory set (chargers, cradles, mounts, spare batteries if applicable)?
This prevents “scope creep,” where a simple mobile payment device sale turns into free integration and support work.
Form Factors: Mobile Pay Device vs Handheld Payment Device vs Portable Payment Device
B2B teams should choose form factor based on workflow and support model—not brand popularity. POS hardware for retail stores may include features like inventory management and optional printer accessories for receipts, providing flexibility for businesses that need to manage stock and offer printed or digital transaction documentation, especially when using single-screen POS terminals and accessories.
Device Class Comparison Table

| Device Class | Pros | Cons |
|---|---|---|
| Phone/tablet + reader | Flexible, familiar UI, easy to swap screens | More parts, pairing issues, inconsistent handling, accessory sprawl |
| All-in-one smart terminal | Fewer moving parts, consistent experience, simpler staff training | Heavier SKU commitment; repairs can mean swapping the whole unit |
| Rugged handheld (operations-first design) | Better drop tolerance, better scanning/printer accessory ecosystems (varies), predictable field handling | Can be overkill if the use case is “one device per counter” with stable power |
A handheld payment device usually implies single-handed operation and frequent movement. A portable payment device may be a broader term that includes countertop-capable devices that can be carried when needed. Your mobile pay device strategy can include both, but you should standardize to a small number of bundles.
Ergonomics and Accessories Affect Support Costs
In multi-store operations, “ergonomics” is not a comfort topic—it’s a ticket volume topic.
Consider:
- Hand strap vs no strap: fewer drops, fewer screen RMAs
- Charging cradle: prevents “charger lost” and inconsistent charging behavior
- Dock/stand: can convert a roaming unit into a semi-fixed lane during peak hours
- Peripheral pairing (if needed): barcode scanner, receipt printer, optional printer, cash drawer triggers (depending on architecture)
When you position a mobile pay device as a repeatable kit, accessories become part of the SKU governance: “same hardware, same cradle, same power profile, same training.”
Payment Acceptance & Security Baseline for Any Payment Device
A payment device is only as good as its reliability under card-present conditions and its security posture across its lifecycle.
Card-Present Operations
For card-present flows, devices should display the contactless symbol to indicate compatibility with contactless cards and digital wallets. Digital wallets like Apple Pay, Google Wallet, and Samsung Pay use tokenization and encryption to secure transactions, replacing card details with a unique, one-time encrypted code. Mobile payment solutions comply with PCI Data Security Standards (PCI DSS) and may be Point-to-Point Encryption (P2PE) certified to ensure transaction security.
When a payment is made, the transaction data is encrypted and sent through a payment gateway for approval, typically completing in seconds. Digital wallets also use biometric authentication, further reducing the risk of theft or fraud. Mobile payment solutions can accept contactless payments from digital wallets, and end-to-end encryption protects both merchant and cardholder data during transactions. Tokenization is used to reduce the risk of fraud and chargebacks, and encryption protects transaction data as soon as it enters the card reader.
- Receipts: After a purchase, digital or printed receipts can be issued, showing the purchase amount. Transaction limits may apply depending on the payment method, and funds are transferred to the merchant’s bank account, often with options for next-day or instant transfers.
What a Card Payment Device Must Handle in Card-Present Operations
Even without going deep into scheme-specific details, B2B buyers should validate that the card payment device can support the card-present flows you’ll see in the field:
- Tap (NFC) for speed and modern customer expectations
- Chip + PIN support where required by local market practice
- Fallback behavior that your POS staff can actually execute correctly (training matters)
- Receipts and acknowledgments aligned with your POS workflow (digital, printed, or both)
For integrators, the key question isn’t “does it support NFC?”—it’s how consistently it supports NFC under real RF conditions, protective cases, and staff handling.
Security Operations You Need to Plan For
Security is not only a certification checkbox; it’s also operational:
- Version control: Can you ensure all deployed devices run approved firmware and payment app versions? Keeping devices updated to the latest version is essential for compatibility with features like Tap to Pay. iPhone requires a supported payment app and the latest iOS version to accept contactless payments, and enabling Tap to Pay may require users to tap download for the necessary software update.
- Key and configuration handling: who loads, rotates, and validates critical configuration?
- Tamper and repair policy: what happens if a device is dropped, opened, or shows abnormal behavior?
- Incident response: how fast can you identify impacted devices and isolate them?
In practice, B2B success often correlates with how well you manage device drift. A mobile pay device fleet that updates “whenever staff remembers” will generate inconsistent behavior and support escalations.
Connectivity, Power, and Uptime: Turning a Device into a Portable Payment System
If you sell or deploy in volume, you’re building a portable payment system, whether you call it that or not. The system is the device plus its operational envelope, much like integrated POS systems for retail and business operations. Mobile payment devices can connect to manage online and in-person payments, streamlining transactions across environments. Some devices also allow for offline transactions, so you can accept payments even when you have a weak or limited connection.
Connectivity: Wi-Fi vs Cellular vs Dual
For payments on the go, assume Wi-Fi will fail sometimes. Then design your connectivity policy:
- Wi-Fi only: workable for indoor queue-busting with strong coverage
- Cellular only: workable for delivery/pop-up—but manage SIM logistics
- Dual (Wi-Fi + cellular): most robust for roaming workflows and high-value transactions
If you support US + UK + EU deployments, connectivity planning must include:
- Carrier coverage differences by region and by store footprint (urban vs rural)
- Roaming policy for cross-border scenarios (especially relevant for EU operations)
- Network isolation practices (guest Wi-Fi vs POS VLAN vs dedicated SSID)
The B2B question isn’t “does the mobile payment device have 4G/5G?” It’s: Can you keep it connected consistently with minimal onsite troubleshooting?
Power: Battery Strategy Is a Shift Strategy
Battery is where many rollouts quietly fail. Decide upfront:
- Per-shift charging model: devices returned to cradles at shift end
- Mid-shift top-up model: brief docking cycles during breaks
- Pool model: spare charged units available to swap instantly
A portable payment device without a disciplined charging method leads to:
- devices being charged at random outlets,
- lost chargers,
- inconsistent battery health,
- and “it died during rush hour” incidents.
If you’re standardizing a mobile pay device kit, treat the charging cradle (or equivalent) as a required component, not an upsell.
Integration Architecture: How a Mobile Payment Device Fits Your POS Stack
Integration determines whether your deployment scales cleanly or becomes a custom integration shop. POS software enables businesses to start accepting payments quickly, often right from the palm of their hand, after downloading the app. Mobile payment solutions can be integrated with existing business applications for streamlined operations, accelerating checkout speeds, reducing transaction costs, and improving security through encryption. Businesses can also manage sales and inventory through integrated software solutions. For companies processing high volumes—such as over $250K in credit card transactions—custom pricing may be available, and funds can be settled as soon as the next business day, ensuring efficient and timely access to your money.
Integration Patterns
Most mobile payment device projects map to one of these patterns, whether you’re deploying a general retail solution or a specialized environment like pharmacy and healthcare-focused POS systems:
- Standalone acceptance + POS reconciliation
- The payment flow happens on the device; the POS records the result.
- Lower integration complexity, but reconciliation and “two-step” workflows must be designed carefully.
- Companion model (POS app + payment component)
- POS app triggers payment; device (or module) handles acceptance.
- Cleaner staff flow, but requires tighter version control.
- Deep integration (single workflow, device is an endpoint)
- Best user experience and reporting consistency.
- Highest governance requirement: releases, testing, certification cycles, staged rollout.
Your selection of a payment device should match the integration pattern. For example, a “best-in-class” device can still be a poor choice if it forces deep integration when your delivery team needs a repeatable companion model.
Fleet Management
B2B rollout success depends on whether you can:
- Provision devices with a consistent baseline
- Control app installation and updates
- Enforce security settings and network policies
- Remote diagnose issues (logs, health checks, connectivity status)
Golden Image Policy
Practically, you should define a “golden image” policy:
- approved OS version range,
- approved payment app version,
- approved POS app version,
- and a staged update plan (pilot → regional rollout → full fleet).
This turns a mobile pay device fleet into an operations-managed asset rather than a collection of consumer gadgets.
Deployment Checklist for Multi-Site Rollouts
Below is a rollout checklist designed for integrators, resellers, and multi-store operators deploying a mobile pay device fleet at scale.
- Define your device bundle: Determine which mobile pay devices will be deployed. Note that some solutions require no extra hardware, allowing a person to accept in-person contactless payments directly on their smartphone or device. Others may include optional accessories available for purchase, depending on your business needs.
- Enable in-person payments: Ensure each mobile pay device is set up so a person can accept in-person payments quickly and securely, without the need for extra hardware.
Step-by-Step Rollout Checklist (SOP)
- Define the device bundle
- Confirm form factor (handheld vs portable) and accessory baseline
- Standardize chargers/cradles and any mounts/cases
- Lock the integration pattern
- Standalone vs companion vs deep integration
- Document the payment flow and error-handling steps that staff will see
- Create a provisioning plan
- Device naming convention (region-store-lane/role)
- Enrollment method (manual vs staged imaging vs automated enrollment)
- Stage and baseline test
- Connectivity tests (Wi-Fi handoff, cellular failover if applicable)
- Payment flow tests (tap/chip/PIN as required by workflow)
- Receipt/confirmation tests in the POS workflow
- Pilot in a representative site
- Choose a site with real peak-hour stress
- Capture: drop points, dead zones, battery pattern, staff adoption friction
- Define support and escalation
- Level 1: store SOP (reboot, dock, network switch steps)
- Level 2: remote helpdesk (logs, version check, device health)
- Level 3: RMA triage and swap policy
- Roll out in waves
- Region-by-region rollout with fixed rollback criteria
- Version freeze windows during peak trading periods
- Post-launch stabilization
- Monitor transaction failure reasons
- Track battery health complaints and charging compliance
- Audit version drift and remediate
This checklist is where the term portable payment system becomes real: the “system” is your provisioning, version control, support model, and swap pool—not just the hardware.
Decision Table: Selecting the Right Mobile Pay Device Class
Use the table below to align stakeholders (procurement, IT, operations, integrators) around a repeatable scoring model.
Tip: Score each category 1–5 and weight it based on the customer’s workflow (e.g., delivery-heavy = higher weight on cellular + durability).
| Selection Factor | Phone/Tablet + Reader | All-in-one Smart Terminal | Rugged Handheld Payment Device |
|---|---|---|---|
| Onboarding & training consistency | Medium | High | High |
| Parts complexity (pairing, accessories) | High | Low | Medium |
| Durability in real field handling | Medium | Medium | High |
| Connectivity resilience (dual modes) | Medium | High (varies) | High (varies) |
| Battery + shift operations | Medium | High | High |
| POS integration repeatability | Medium | High | High |
| Fleet management suitability (MDM, control) | Medium | High | High |
| Repair strategy (swap vs component) | Medium | High (swap unit) | Medium–High (depends on design) |
| Best fit for “payments on the go.” | Medium | High | High |
| Where each class wins: |
- Choose phone/tablet + reader when you need flexibility, and you already manage mobile endpoints well, and the environment is not harsh.
- Choose an all-in-one mobile payment device when you want consistent staff flow, fast onboarding, and fewer pairing issues.
- Choose a handheld payment device when operations are rugged, movement-heavy, and you need predictable survivability and swap logic.
This is also where keyword language matters: some buyers search “card payment device” because they’re focused on acceptance, while others search “portable payment device” because they’re focused on mobility. Your product bundles should satisfy both discovery paths.
Note: Certain payment technology symbols, such as the Contactless Symbol, are trademarked and may require official licensing for use in branded materials.
Spares, Repairs, and Lifecycle: Keeping the Fleet Running
B2B buyers rarely lose money because they chose the “wrong feature.” They lose money when the fleet becomes unserviceable.
Build a Swap Pool and an RMA Triage Path
For multi-site operations, define an RMA strategy that avoids downtime:
- Swap-first policy: replace quickly, investigate later
- Triage categories:
- “No power/battery issue”
- “Network issue”
- “Payment flow failure”
- “Physical damage”
- “Software/version mismatch”
A disciplined swap pool reduces store disruption and keeps integrator support costs predictable. If you’re distributing a mobile pay device in volume, your spares strategy is a sales enabler: it converts “downtime fear” into “we have a plan.”
Lifecycle Governance: Version Cadence and End-of-Life Risk
Device fleets fail quietly when:
- OS updates break the POS app or payment components
- Hardware revisions change behavior
- Vendors end support earlier than expected
To protect deployments:
- Maintain a version support matrix (device model → approved OS versions → approved POS/payment versions)
- Run quarterly health checks (version drift, battery health trends, failure codes)
- Define an end-of-life plan (final supported versions, replacement windows, swap pool ramp-down)
For US/UK/EU customers, governance helps with internal audits and vendor management expectations, even when exact regulatory requirements differ by market, aligning with how global POS solution providers structure their operations and compliance.
Bringing It Together: A Practical Selection Approach
To choose a mobile pay device that will survive B2B reality, don’t start with a spec sheet. Start with:
- Workflow constraints (your “payments on the go” story)
- Integration pattern (how the device talks to the POS stack)
- Operational envelope (connectivity, charging, staff behavior)
- Support and lifecycle (swap pool, RMA triage, version governance)
Then map those needs to a device class and bundle. Do that consistently, and your offering becomes easier to sell, easier to deploy, and easier to support—exactly what integrators, resellers, and multi-store procurement teams value.


POS Port Map vs Compatibility Matrix: What Deployment Teams Need Both Documents For

Presentation Scanner vs Handheld Scanner at Checkout: Which Counter Setup Creates Fewer Support Tickets?

POS Counter Installation Audit: How to Catch Power, Cable, and Mounting Risks Before Go-Live

EU POS Hardware Import Checklist: CE, RoHS, WEEE, and RED Checks Before You Buy from China

Self-Checkout Support Ticket Triage: How to Separate Scanner, Payment, Scale, Printer, and Workflow Errors

Self-Checkout Cameras vs Bagging Scales: What Prevents More Shrinkage?

POS Support Ticket Triage: How to Separate Hardware Failure, Network Instability, Configuration Drift, and Workflow Error

Retail Barcode Label Printer Compatibility: What Must Match Between POS, Inventory App, and Scanner

Duplicate Kitchen Tickets in Multi-Printer POS: What to Check Before Replacing Hardware


