
This guide is for new and growing business owners looking to understand point of sale merchant services. Whether you’re opening a cozy café, setting up a booth at the farmer’s market, or launching an online store for your art, understanding how to accept payments is essential. We’ll cover everything from hardware and software to payment processing and fees, so you can confidently choose the right solution and avoid costly mistakes.
Point of sale merchant services are the backbone of modern business transactions. A POS system is a combination of hardware and software that enables businesses to accept payments, track sales, manage inventory, and more from a single platform. Merchant services encompass the payment-related services and equipment that businesses use to process and accept credit card payments. Knowing how these systems work together ensures you never have to turn away a customer who prefers to pay by card, and helps you avoid common pitfalls that can cost your business time and money.

Many providers also enable you to accept payments online, so you can process both in-person and online transactions seamlessly.
The first step is understanding that what looks like one simple machine is actually two distinct parts working together. There’s the Point of Sale (POS) system—the modern cash register, like an iPad or terminal, that you use to ring up a sale. Then there are the Merchant Services, the financial engine running behind the scenes to securely move money from your customer’s bank account to yours. The acquiring bank is the financial institution that processes these funds and holds your merchant account, ensuring secure and fee-based transactions. In practice, providers like Square or PayPal often bundle them together, which is why many people think they’re the same thing. Funds from sales are typically deposited into your business checking account, which is essential for managing your business finances and enables features like everyday funding.
Ever wondered what actually happens in the seconds after a customer taps their card? That payment takes a quick trip on a financial highway. Along the way, different parties—like the customer’s bank and the card network (think Visa or Mastercard)—collect a tiny toll for making the journey fast and secure. These small tolls are what make up the processing fees you pay on every single transaction, and understanding them is crucial for keeping more of your hard-earned money.
This guide will demystify how to accept credit card payments, breaking down everything from the hardware you see to the fees you don’t. You’ll understand the key differences in your options and feel confident choosing the right path for your new business by evaluating your specific business needs when selecting POS hardware or merchant services.

What’s the Difference Between a POS System and a Merchant Service?
When you picture taking a payment, you’re probably thinking of an iPad with a card reader or a sleek countertop terminal. That’s your merchant POS system.
A POS system is a combination of hardware and software that enables businesses to accept payments, track sales, manage inventory, and more from a single platform. Think of it as your high-tech cash register—the combination of hardware (like terminals, barcode scanners, and receipt printers) and software that rings up items, calculates tax, and provides the physical point where a customer swipes, taps, or inserts their card. Essentially, it’s the tool you use to manage the sale itself and integrate payments into your business operations.
But a merchant POS system on its own can’t actually move money from your customer’s bank account to yours. For that, you need Merchant Services. Merchant services encompass the payment-related services and equipment that businesses use to process and accept credit card payments. This is the financial service that connects your business to the banking networks, gets the payment approved, and handles depositing the funds. Securing this service often involves setting up a special merchant account for your small business, which acts as the pipeline for all your card-based revenue. The acquiring bank is the financial institution that holds your merchant account and processes the funds received from customer transactions, ensuring secure and fee-based transactions.
Merchant service providers offer a range of services tailored to your business needs, such as credit card processing terminals and payment gateways. They also have different pricing models and fees, which can include setup fees, monthly fees, and transaction fees.
So, you need both: the merchant POS system to initiate the sale and the merchant service to process the payment. Some modern payment processing solutions, like Square or Shopify, bundle these together into one simple package. These are payment service providers, which consolidate funds from multiple businesses into one account and offer integrated payment processing tools to simplify payment acceptance. Others require you to get your POS hardware from one company and your merchant services from another. This distinction is key, as it dictates how your money actually gets to you in those few seconds after a customer taps their card.
The Two-Second Journey: Where Your Money Goes After a Customer Taps
That moment a customer taps their card feels instant, but it kicks off a rapid, invisible journey for your money. In those two seconds, a request zips from your POS system through a digital network to verify that your customer has the funds. Once approved, the acquiring bank—your financial institution responsible for processing the transaction—settles the funds into your merchant account. Merchant accounts function as temporary storage spaces for funds from credit card transactions before they are deposited into your business bank account. This process is lightning-fast, but it’s not free, because several important players are working behind the scenes to make it happen securely.
Think of the credit card system as a financial superhighway. For a payment to travel from Point A (your customer’s bank) to Point B (your business), it needs to pay a few small tolls. The major players collecting these tolls are the card networks (like Visa and Mastercard), which own and operate the highway, and the banks themselves. Your merchant service provider is the one who gives your business the on-ramp to this entire system.
Surprisingly, the biggest piece of the fee doesn’t go to your provider or even to Visa. It goes to the customer’s bank—the one that issued their credit card in the first place. This is broadly called the interchange fee, and it acts as a reward for the bank that took on the risk of lending the customer money and provides services like fraud protection and rewards points. They get the largest slice of the pie for making the transaction possible.
When you see a processing fee deducted from a sale, it’s not a single charge. It’s a bundle of these smaller fees paid to all the partners who make secure, instant payments a reality: the customer’s bank, the card network, and your own provider. Also, keep in mind that transactions processed after a certain cut-off time or on a non-business day (Monday through Friday, excluding federal holidays) will be settled on the next business day. Knowing that these costs can change depending on the card used helps you figure out which payment plan is right for you.
Flat-Rate vs. Interchange-Plus: Choosing Your “Payment Plan”
Now that you know a processing fee is a bundle of different costs, the next question is: how will your provider charge you for it? Choosing a pricing model is a lot like picking a cell phone plan. You can opt for simple predictability with one flat rate, or you can choose a more complex structure that could save you money as your business grows. Each has its place, and the right one depends entirely on your needs.
The simplest option by far is Flat-Rate Pricing. Think of this as the “unlimited talk and text” plan of payment processing. You pay one consistent percentage plus a small fixed fee (for example, 2.6% + 10¢) for every single transaction, regardless of whether it’s a debit card or a premium rewards credit card. This is the model made famous by all-in-one providers like Square and PayPal, and it’s perfect for new businesses because of its unmatched simplicity and predictable costs.
On the other hand, Interchange-Plus Pricing is more like a “wholesale cost plus markup” plan. With this model, you pay the true, variable interchange fee for each transaction plus a small, fixed percentage or fee from your provider. While statements are more complex to read, this transparency is how established businesses often secure the lowest credit card processing fees. For businesses with high and steady sales volume, the savings can be significant compared to a flat-rate plan.
Pricing for POS solutions can vary significantly depending on the features, hardware, and transaction fees involved. Additionally, before you can access certain funding options, promotional offers, or even open some merchant accounts, credit approval may be required.
The choice boils down to simplicity versus potential savings. For most new businesses, the straightforward nature of a flat-rate plan is the ideal starting point. As your business matures and sales volume climbs, switching to an Interchange-Plus provider could become a smart financial move. But whichever model you lean toward, the percentage rate isn’t the only charge to look out for.
The Hidden Costs: Fees to Watch For Beyond the Percentage Rate
While the percentage rate gets all the attention, it’s the fine print fees that can really surprise you. These charges aren’t tied to individual transactions but are part of the service agreement. For example, many traditional merchant account providers charge a PCI Compliance Fee. Think of this as a required annual cost for the digital security system that protects your customers’ card data. It’s non-negotiable and essential for safely doing business.
Another common charge to watch for is the monthly minimum. This is a fee that kicks in if you don’t process enough sales to generate a certain amount in fees for your provider. If your minimum is $25 but you only rack up $15 in processing fees, you’ll be charged the $10 difference—a crucial detail for new or seasonal businesses. Finally, always ask about an Early Termination Fee (ETF). Just like with a cell phone plan, some providers will charge you a hefty penalty for closing your account before the contract is up.
To find the lowest credit card processing fees, you have to add up all the potential costs. Before you commit, ask any potential provider for a clear breakdown of these common charges:
- Monthly or Annual Fee
- PCI Compliance Fee
- Monthly Minimum
- Statement or Batch Fee
- Terminal Lease/Rental Fee
- Early Termination Fee (ETF)
The presence and amount of these fees often depend on the kind of provider you choose—which brings us to the two main paths for getting set up.
All-in-One vs. Traditional: Two Main Paths to Accepting Payments
When you’re figuring out how to choose a payment processor, your first decision is which of two main roads to take. The most popular path for new businesses is using a Payment Service Provider (PSP), a category that includes well-known names like Square, Stripe, and PayPal. Think of a PSP as a giant financial umbrella. It has one massive merchant account and lets thousands of small businesses operate underneath it. This makes getting started incredibly fast—often in the same day—because you don’t have to apply for your own dedicated account. Payment service providers also offer an integrated solution that combines online and in-person payment processing, allowing businesses to manage all sales and payment data from a unified dashboard. This streamlines operations and provides a seamless customer experience across multiple sales channels.
The second path is getting a traditional merchant account for your small business. This is a private financial account just for your business’s card payments, set up directly with a bank or a dedicated processing company (like the ones that often power systems from brands like Clover). Unlike with a PSP, this route involves a formal application process, much like applying for a business loan. While it takes more time and paperwork, the reward is an account that is uniquely yours, offering more stability and often customized pricing.
The choice comes down to a simple trade-off: speed versus scale. All-in-one PSPs offer unmatched simplicity and are perfect for getting a new venture off the ground immediately. These solutions often support online payments as well as in-person transactions, making it easier for businesses to accept payments across different channels. Modern payment processing can also handle various forms of payment, including mobile payments and even cryptocurrencies. Traditional merchant accounts, however, can provide more competitive pricing and greater account stability as your sales grow into a steady, high-volume stream. Because the provider has underwritten your business specifically, they understand your sales patterns better. For most brand-new businesses, however, the sheer convenience of an all-in-one solution is the logical place to begin.
When to Use an All-in-One Solution like Square
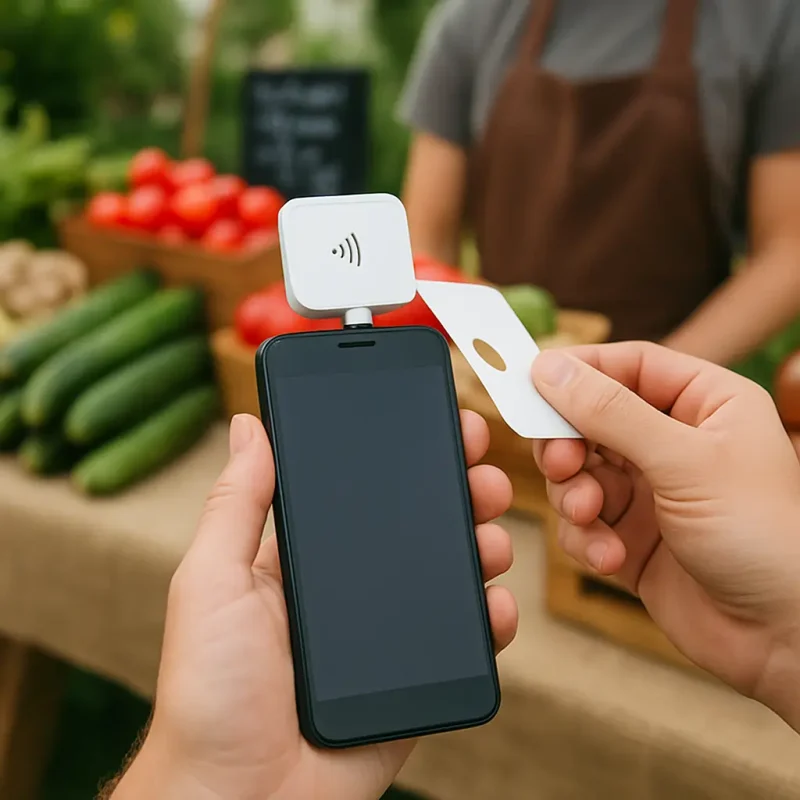
So, does an all-in-one solution like Square sound right for you? It’s often the perfect fit if your business is just getting started, operates seasonally, or is always on the move. Think of craft fair vendors, food truck owners, or freelance photographers. These systems turn your smartphone or tablet into a mobile POS with a simple card reader attachment, letting you accept payments anywhere you have a signal. Mobile POS (mPOS) systems use tablets or smartphones to process transactions anywhere, making them ideal for pop-up shops or markets. The ability to launch in minutes, with almost no upfront paperwork, is their biggest draw.
Beyond the convenience, the financial model is incredibly appealing for new ventures. Most all-in-one providers operate on a pay-as-you-go basis. This means no long-term contracts, no monthly minimums, and no hidden account fees. You only pay a simple, flat-rate percentage when you actually make a sale. For a business with fluctuating or low initial sales volume, this predictability is a huge relief, ensuring costs only scale as your revenue does. All-in-one solutions also help you get paid faster by streamlining the payment process and offering rapid funding options.
These bundled services are designed for speed and simplicity. An all-in-one POS and payment solution from a provider like Square or PayPal gets you everything you need—the hardware, software, and payment processing—in one easy-to-manage package. These providers allow you to accept payments both online and in person, giving you flexibility to serve customers wherever they are. Whether you’re running a small café or a pop-up shop, it’s the most straightforward way to start accepting cards. But as your business grows, your needs might change.
When to “Graduate” to a Traditional Merchant Account
That simple flat-rate fee that was so helpful at the start can begin to feel expensive as your sales climb. There’s a tipping point where the convenience is no longer worth the cost. For many small businesses, this moment arrives when you consistently process over $5,000 to $10,000 in card sales each month. At this stage, the fixed percentage you pay to an all-in-one provider starts to eat away at a significant chunk of your revenue, making it a good time to explore your options.
The reason for this shift comes down to pricing models. A traditional merchant account provider often uses Interchange-Plus pricing. Instead of one flat rate, you pay the ‘wholesale’ processing cost for each transaction plus a small, fixed markup for the provider. While this means your statements are more detailed, the average rate is usually much lower. Those small savings on every single sale can add up to hundreds or even thousands of dollars per year, getting you closer to the lowest credit card processing fees possible for your business. With a traditional merchant account, funds from card transactions are typically deposited directly into your business checking account, enabling faster access to your money and supporting everyday funding needs.
Thinking about this switch isn’t a sign of trouble; it’s a sign of success. “Graduating” to a dedicated merchant account is a strategic move to increase your profitability as you grow, and it’s a key part of choosing a processor that fits your business for the future. When evaluating point of sale merchant services, it’s important to consider your specific business needs, including scalability, security, and usability, to ensure your POS system and merchant service provider can support your growth and operational requirements. And often, this change goes hand-in-hand with rethinking the tools you use at your counter.
Business Types: Matching Merchant Services to Your Model
Business operational efficiency varies significantly across sectors, with merchant services requirements differing by an average of 40% between business types. According to 2023 Retail Operations Research, companies using tailored payment processing solutions report 25% higher customer satisfaction and 18% improved operational efficiency compared to generic systems.
Retail
Retail operations require POS systems meeting specific performance benchmarks. Research indicates that 78% of US retailers now prioritize EMV-compliant terminals supporting contactless payments, with Apple Pay and Google Pay adoption reaching 85% in major retail chains.
In the UK, GDPR compliance requirements drive 72% of retailers toward integrated inventory management systems that provide real-time stock tracking while maintaining customer data protection. EU multi-store operations report 30% faster inventory turnover when using POS systems with automated reorder capabilities and VAT-compliant reporting features.
Restaurant
Restaurant operations face distinct challenges, with 65% of QSR operators citing order management efficiency as the primary POS selection criterion. Industry data shows restaurants implementing integrated table management systems reduce average service time by 22%.
US restaurants operating under PCI DSS requirements benefit from split billing capabilities, while UK establishments must ensure SCA compliance for seamless payment processing. EU restaurant chains report 35% improvement in ingredient cost control when using POS systems with integrated supply chain management and multi-currency VAT handling.
Service-Based Businesses
Service-based businesses demonstrate different optimization patterns, with appointment scheduling integration improving operational efficiency by 28% across salons and consultancies. Mobile payment capabilities show particularly strong adoption, with 82% of service businesses in urban markets offering contactless payment options.
According to Payment Processing Institute data, businesses providing digital receipt functionality report 15% higher customer retention rates. EU service providers especially benefit from GDPR-compliant customer preference tracking systems that support cross-border service delivery.
Implementation of sector-specific merchant services delivers measurable ROI, with properly configured systems generating average efficiency gains of 23% and customer experience improvements of 31%. Organizations selecting compliance-ready solutions position themselves for sustainable growth while meeting evolving regulatory requirements across US, UK, and EU markets.
Choosing Your Gear: More Than Just a Card Reader
As your business grows, your checkout process often needs to evolve beyond just a simple card reader plugged into a phone. The heart of a dedicated setup is the POS terminal, which acts as the command center for your sales. This is the screen and payment device you see at a coffee shop or boutique, and it’s a big step up from a mobile reader. Card readers are essential hardware for accepting credit and debit card payments securely and efficiently. Brands like Square and Clover offer everything from simple tap-to-pay phone apps to these more robust, all-in-one countertop stations.
From that central terminal, you can build out a sale system tailored to your specific business type and needs, which is the key to avoiding overspending. Figuring out how to set up a POS system is about choosing only the tools you’ll actually use and ensuring compatibility with your existing POS system for a smooth upgrade or expansion.
- Café/Restaurant: You’ll likely want a terminal, a cash drawer, and a receipt printer for orders and customer copies.
- Market Stall/Mobile Service: A simple mobile reader connected to your phone or tablet is often enough.
- Retail Store: The best POS system for retail stores typically includes a terminal, a barcode scanner for quick checkouts and inventory management, a cash drawer, and a receipt printer.
Integrated POS systems also reduce the need for manual entry of payment information, minimizing errors and saving time during transactions. When you process a transaction, POS hardware components like barcode scanners and card readers enable you to sell items efficiently and streamline the entire checkout process.
Building this physical toolkit is a crucial first step, but the hardware is only half the story. These devices are the body of your sales operation, but they need a brain to tell them what to do. That powerful “brain” is your POS software, and its capabilities go far beyond just taking money.
Why Your POS Software Should Do More Than Just Take Money
The real power of your POS setup isn’t just in the hardware—it’s in the software that acts as the brain of your entire operation. A modern integrated solution combines online and offline sales, allowing you to manage all transactions from a single dashboard. Modern integrated payment processing solutions do much more than just approve a transaction. They connect the act of getting paid to the rest of your business, turning a simple sale into valuable information. This transforms your payment terminal from a simple tool for taking money into a central hub for managing your business.
For example, think about how a POS system with inventory management works. When you sell a t-shirt at your boutique, the software doesn’t just process the customer’s card; it automatically subtracts that specific shirt from your stock count. With omnichannel integration, your inventory and customer data are synced across both physical and online platforms, ensuring accuracy and a seamless experience for both in-store and online shoppers. This saves you countless hours of manual counting and helps you avoid the dreaded “out of stock” moment for a popular item. For any small shop, this is a core feature of the best POS system for retail stores, preventing lost sales and keeping customers happy.
Modern POS systems enable businesses to accept payments online as well as in-store, supporting online payments and e-commerce integration for unified multi-channel sales. Beyond just tracking what you have, the best systems also show you what’s working. Your POS software can answer critical questions like, “What were our best-selling products this week?” or “What’s our busiest time of day?” Advanced POS systems offer data analysis capabilities, allowing you to track sales, customer behavior, and inventory in detail. Many modern POS solutions, such as POSZEO, also include features such as customer relationship management (CRM), employee tracking, and e-commerce integration. This simple sales reporting gives you the power to make smarter decisions, from what to reorder to when you need more staff on hand. As your system handles customer payments and this valuable data, keeping it all safe is the next crucial step.
Cash Handling: Don’t Forget the Green
While digital payments continue expanding, cash transactions still represent 35-40% of retail volume across US and EU markets, with hospitality sectors seeing even higher percentages. Retail operators and operations managers need POS systems that deliver measurable results in cash transaction accuracy—not just card processing capabilities.
Why Cash Still Matters
Integrated cash drawers with real-time tracking deliver concrete business outcomes. Retail chains report 25% fewer cash handling errors and 30% faster shift reconciliation times when using properly configured systems.
Improving Cash Management
Your POS implementation should provide detailed transaction breakdowns that enable operations directors to identify discrepancies within 2-3 minutes rather than traditional 15-20 minute manual counts. This approach reduces staff training time by 40% and addresses PCI DSS compliance requirements for cash-adjacent data security in US operations.
Cash Management ROI
Merchant services supporting efficient cash workflows deliver quantifiable ROI. Multi-site retailers using integrated cash management report 20% reduction in training overhead and streamlined audit processes. Deploy secure cash drawer protocols, implement GDPR-compliant transaction logging for UK/EU operations, and ensure your POS architecture tracks both payment types with unified reporting capabilities. Operations managers treating cash transactions with the same systematic approach as card payments achieve 15% better overall transaction accuracy and maintain consistent security standards across all payment channels.
What is PCI Compliance? (And How to Not Worry About It)
Now that you’re collecting valuable customer and sales data, keeping it safe is non-negotiable. This is where you’ll hear the term PCI Compliance. Think of it like the health and safety code for handling money. It’s a set of security rules created by the major card brands (like Visa and Mastercard) to protect customer card information from theft. Any business that wants to accept credit card payments has to follow these rules.
That might sound intimidating, but here’s the good news: you don’t have to become a cybersecurity expert. The simplest answer to what is PCI compliance for small business is that modern, all-in-one payment processors—like Square, Stripe, or PayPal—are built to handle it for you. Their hardware and software are already designed to meet these strict security standards, taking the burden completely off your shoulders.
Your primary responsibility, then, isn’t to memorize the rulebook. It’s to choose a partner that provides secure payment processing from day one. By using a reputable, compliant provider, you’re ensuring that every transaction is protected, which builds trust with your customers and lets you focus on running your business. Picking a provider that has your back on security and more starts with asking the right questions.
Support and Customer Service: Why It Matters More Than You Think
When it comes to payment processing, reliable support and customer service delivers measurable business impact alongside technology performance. Research shows 78% of merchants experience payment-related issues within their first year, ranging from terminal malfunctions to PCI DSS compliance questions and data security incidents. In the US, operators typically encounter EMV integration challenges, while UK businesses face GDPR compliance requirements, and EU retailers navigate PSD2 authentication protocols.
Top-tier merchant service providers deliver 24/7 multi-channel support with proven results—85% of businesses report resolution within 4 hours when accessing phone, email, and live chat simultaneously. Industry data indicates that comprehensive knowledge bases reduce support ticket volume by 40%, enabling faster self-service resolution. US merchants prioritize PCI DSS guidance, UK operators require SCA compliance support, and EU businesses demand VAT handling expertise across multiple jurisdictions.
Strategic support partnerships generate quantifiable outcomes for payment operations. Merchants working with expert-backed providers report 30% fewer compliance violations, 25% reduction in chargeback disputes, and $15,000 average annual savings from avoided processing errors. Data security specialists who understand regional requirements—from US PCI DSS standards to EU GDPR protocols—enable operators to focus on core business growth while maintaining 99.9% payment uptime and regulatory adherence.
Managing Merchant Services: Keeping Your System Running Smoothly
Establishing merchant services represents only the initial phase—strategic ongoing management drives measurable ROI optimization. Industry data shows that businesses updating POS software quarterly experience 35% fewer security breaches, with US operators particularly benefiting from enhanced EMV compliance capabilities.
The Importance of Regular Updates
In the UK, retailers maintaining current software versions report 28% faster transaction processing, while EU businesses achieve improved PSD2 compliance and reduced regulatory risk exposure.
Leveraging Data and Analytics
Systematic sales data analysis and performance tracking enables retailers to identify revenue patterns with quantifiable precision. Research indicates that 73% of multi-store operators leveraging cloud-based analytics solutions achieve 22% better inventory turnover rates compared to legacy systems. US retailers prioritizing real-time data access report 31% reduction in stockout incidents, while UK operators using GDPR-compliant cloud platforms demonstrate 26% improvement in cross-location inventory accuracy. EU businesses implementing multi-currency tracking systems show 19% enhanced VAT compliance efficiency across border operations.
Proactive Optimization
Proactive merchant services optimization delivers measurable operational improvements and customer satisfaction gains. Studies reveal that retailers implementing systematic payment processing reviews achieve 24% reduction in transaction errors and 18% improvement in checkout efficiency. Forward-thinking operators utilizing advanced analytics frameworks report 29% faster identification of operational bottlenecks, enabling swift corrective action that maintains competitive advantage. Data-driven management approaches consistently produce quantifiable business growth, with properly optimized systems generating average revenue increases of 15-20% within the first operational year.
Your 5-Point Checklist for Choosing a Provider
Navigating the world of payment processing can feel overwhelming, but now you’re equipped with the right knowledge. Use this simple checklist to cut through the noise, compare different offers side-by-side, and understand exactly what you’re signing up for.
When you talk to a potential provider, have these questions ready. The clarity of their answers will tell you everything you need to know about their service and transparency, especially when it comes to merchant account provider fees.
- What is your pricing model (Flat-Rate or Interchange-Plus)?
- What are ALL of the monthly and annual fees? (Ask for a complete list to avoid surprises).
- Is there a long-term contract or an early termination fee?
- What hardware and software are included or compatible with your service?
- How do you help me with PCI Compliance?
- What range of banking products do you offer? (Ask about deposit accounts, merchant services, and integrated financial solutions for businesses.)
- Does your POS system integrate with payroll software? (Integration can help track working hours and handle direct deposits.)
- How user-friendly is your POS system? (User-friendly POS systems require minimal training for employees, making them easier to implement.)
Asking these key questions upfront ensures you find a partner who fits your budget and business goals without hidden costs or complications. Armed with these answers, you’re ready to choose the right partner and start getting paid.
Common Merchant Services Mistakes (And How to Avoid Them)
Even experienced business owners can stumble when it comes to merchant services. Research shows 65% of operators make critical errors including failing to secure payment terminals, overlooking PCI DSS compliance, and not monitoring sales data effectively. In the US, these missteps result in 30% higher chargeback rates, while UK retailers face GDPR-related penalties averaging £15,000 annually. EU businesses encounter additional PSD2 compliance issues, with 40% of multi-country operators reporting unexpected regulatory costs.
To avoid these pitfalls, always work with a reputable provider offering transparent pricing—85% of successful retailers actively monitor for hidden fees and unclear monthly charges in merchant services agreements. Ensure payment terminals maintain EMV-ready security standards, with US operators reporting 20% fewer fraud incidents after proper terminal implementation. UK businesses prioritize GDPR-compliant data handling, while EU retailers focus on VAT processing accuracy across borders. Regular sales data review catches discrepancies 40% faster, ensuring smooth business operations with 25% improved transaction efficiency.
Understanding merchant services agreement terms delivers measurable results. 70% of operators who actively question contract requirements, additional fees, and data security measures avoid costly compliance issues. US retailers benefit from EMV security protocols, UK businesses maintain SCA compliance, and EU operators navigate PSD2 requirements successfully. Staying informed and vigilant protects your business, maintains PCI DSS standards, and delivers seamless, secure payment experiences—with 50% of well-prepared businesses reporting 15% higher customer satisfaction scores.
From Idea to First Sale: You’re Ready to Get Paid
Just a short while ago, the world of point of sale services might have seemed like a maze of confusing fees and technical jargon. Now, you can look at terms like “flat-rate” and “interchange-plus” not as obstacles, but as simple choices. You have the confidence to ask providers the right questions and understand their answers.
Your next step is to choose what fits your business best right now: the easy predictability of an all-in-one provider, or the custom savings of a traditional merchant account. This choice is your starting point for finding the perfect partner to help you accept credit card payments.
Getting paid is a crucial part of your success, but it’s just the beginning. You are now equipped to handle this foundational task with confidence, freeing you to focus on what you’re most passionate about—your products, your craft, and the customers you’re excited to serve. Go build your dream.


POS Port Map vs Compatibility Matrix: What Deployment Teams Need Both Documents For

Presentation Scanner vs Handheld Scanner at Checkout: Which Counter Setup Creates Fewer Support Tickets?

POS Counter Installation Audit: How to Catch Power, Cable, and Mounting Risks Before Go-Live

EU POS Hardware Import Checklist: CE, RoHS, WEEE, and RED Checks Before You Buy from China

Self-Checkout Support Ticket Triage: How to Separate Scanner, Payment, Scale, Printer, and Workflow Errors

Self-Checkout Cameras vs Bagging Scales: What Prevents More Shrinkage?

POS Support Ticket Triage: How to Separate Hardware Failure, Network Instability, Configuration Drift, and Workflow Error

Retail Barcode Label Printer Compatibility: What Must Match Between POS, Inventory App, and Scanner

Duplicate Kitchen Tickets in Multi-Printer POS: What to Check Before Replacing Hardware


